The majority of home insurance policies offer at least some level of flood damage as part of their buildings and contents cover, safeguarding the structure of your property and what’s inside. However, if you live in a high-risk area, it can be harder to find a policy – you may need to look for a flood insurance specialist.
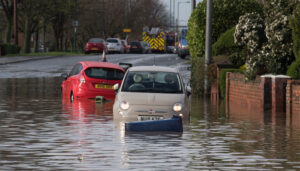
Considering how flooding poses a serious threat for 2.4 million UK residents, especially those living in areas prone to heavy rainfall and coastal regions, it’s imperative you have cover. Last year, some UK regions suffered the wettest weather since 1766, when records began.
Coastal areas such as Cornwall, Hull, Great Yarmouth, Peterborough, Sussex and Kent suffered severe flooding, while rivers burst their banks in Somerset, Cambridgeshire, Essex, Norfolk, Yorkshire and Lincolnshire, leading to misery for thousands of residents.
 © JordanCrosby / Shutterstock.com
What should you look for in home insurance?
Your flood insurance should cover the costs of repairs, replacements, or even a rebuild of your home, depending on how badly your property is damaged. You must read the policy properly to ensure it covers flooding caused by nature including overflowing rivers and canals, and heavy rainfall. Flooding caused by “escape of water” (burst pipes or water mains issues within your home) is covered under a different section of your insurance policy.
Flooding can cause extensive and costly damage to your buildings and contents, including your furniture, so it’s important you read the small print of your policy. If you live in a high-risk area, or your home has been flooded before, you may have to pay more.
However, don’t let this deter you when it comes to cover. Data from Money Supermarket shows consumers whose home has been flooded pay £199 a year on average for a home insurance policy. This compares with £96 per year for people who haven’t made a flood insurance claim – a small price to pay, though, when you consider the costs of flood damage.
More than 82,000 UK householders claimed for flood and wind damage after suffering the effects of storms Ciara and Dennis in February 2020, according to the Association of British Insurers. The total cost of repairing homes and business premises after the storms was around £360 million.
Are there special clauses for high-risk areas?
If you’re looking for home insurance for flood risk areas, check out specialist insurers online and get a quote from their website.
You will probably be asked specific questions about your property. These could include whether your home is within 200 metres of any bodies of water, how high it is above the waterline and whether it has flooded in the past. If you have had floods previously, you may be asked the date it last occurred, how badly your buildings were affected and how high the floodwater rose.
You may also be asked if any precautions have been taken since, such as erecting anti-flood barriers or installing sandbags. The insurer will decide whether they can give you cover and how much it will cost, based on your answers.
It’s a good idea to compare as many quotes as possible to try and save money. By being honest and upfront with your answers, you will avoid problems later on, in the event of a claim. You also need to make yourself aware of any clauses added to the policy – always read the small print before signing anything.
How do I know if I’m in a flood risk area?
Find out if your home is at a high risk of flooding by checking on the Gov.uk website, where you will find a flood map of the UK – you will need your postcode or national grid reference.
People in England can apply to the Environment Agency for a free insurance-related letter. It will detail previous floods and assessments and planned improvements for your area to pass on to your insurer.
In practical terms, if you are in a high-risk area, keep your most treasured possessions upstairs, or on high shelves downstairs. You could take photos of your interior so that in the event of a flood, you can show “before” and “after” photos to your insurer.
If you need to make a claim, first tell your insurer exactly what has happened. Then, gather evidence, which can include videos. You will need to check how deep the water is – this must be done before you start cleaning up. Check your insurer doesn’t require any more information before you do anything.
How bad have storms been so far in 2021?
Storm Christoph is the first named storm to hit Britain in 2021, causing an amber warning for parts of Yorkshire, including Bradford, York and Huddersfield. The River Ouse burst its banks, causing severe flooding in York. Around 400 homes have been flooded to date.
Other storms are predicted throughout the year, including Storm Darcy, but currently, there are only long-range forecasts in place. With the tail end of Storm Christoph still on UK shores, plenty of people are already having to mop up the flood damage.
If you’re unlucky enough to suffer flooding, first contact your insurer to make your claim. Then, contact Furniture Rental Online for information about our emergency furniture – we can provide an affordable solution to help you get through the crisis.
We can help insurers, claims handlers and loss adjusters to complete your claim in the event of an emergency.